
August 24, 2026

Recibe las últimas novedades sobre propiedades, informes de mercado y análisis de expertos directamente en tu bandeja de entrada.

Tax incentives, among other benefits, have drawn the ultrawealthy to the city. And they need space for the firms that manage their money.

MEDIA CONTACT: Levy Public Relations
The billionaire investor Peter Thiel broke rental records in June when he leased space in Miami’s Brickell neighborhood for $250 a square foot for his family office. The same month, the billionaire Mohamed Mansour of Man Capital signed a family office lease in the Well, a new complex in Bay Harbor Islands. The Super Bowl champion Tom Brady is getting ready to move his family office, TEB Capital Management, into the same building.
Those moves and others like them have begun to change Miami’s office landscape, part of a growing wave of firms opening there to manage an individual’s wealth and private affairs. As more high-net-worth individuals have migrated to Miami since the Covid-19 pandemic, the need for these private firms there has increased, too.
Single-family offices, tracing their roots back to the Rockefellers in the 19th century, have grown substantially this decade. In 2024, there were more than 8,000 single-family offices globally, up about 30 percent from just over 6,000 in 2019, according to the latest report on family offices by Deloitte. That number is expected to exceed 10,000 by 2030, or roughly 75 percent growth over 10 years.
The rise comes from the rapid increase in the concentration of wealth. In 2024, the total estimated wealth of families with family offices was more than $5 trillion, compared with a little over $3 trillion in 2019, according to Deloitte. More money leads to more complex holdings, and accountants, tax experts and other firms have emerged to fill the gaps.
In Miami, brokers have had to move unusually fast to keep up with the pace of requests recently for family office space. During the second quarter of 2026, 15 percent of new leasing activity in Miami was tied to financial service expansions, which include family offices, according to a report from Blanca Commercial Real Estate, an independent brokerage and advisory firm.
The average assets under management of family offices was $2 billion in 2023, according to the Deloitte survey of 354 single-family offices around the world, including those of prominent families. More than 120 are already set up in the Miami area, with median assets under management of $350 million, according to research from Altss, which tracks family office data.
Now, more families outside the ultrahigh-net-worth tier are requesting office space.
“Twenty years ago, it was the uber wealthy and it was very investment focused,” said Lee-ford Tritt, a professor at the University of Florida’s Levin College of Law who focuses on estate planning. “Now they’ve become very much management vehicles for families with very complex holdings.”
The rising demand in office space has led to higher, more competitive leasing prices, analysts and real estate leaders said. Between 2020 and 2025, average asking rents for office space in Miami-Dade County increased more than 50 percent, according to data from Blanca and JLL, a real estate services firm.
During that period, according to the report, comparable markets did not see such steep growth. Austin, Texas, rents increased by almost 18 percent, Dallas by 13 percent and Raleigh, N.C., by 8 percent. New York City and San Francisco experienced declines, with average asking rents falling 10 percent and 15 percent.
“In New York, one building gets filled up and it’s a big deal, but it’s not a market changer,” said Brian Gale, the vice chairman of Cushman and Wakefield in Florida. “In Miami, because our market is so much smaller than New York or Chicago or Northern California, our rents went up two to three times” what they were before a huge wave of people moved to Miami during the pandemic, he said.
Miami, West Palm Beach and Boca Raton already have the lowest rates of office vacancies among the largest national markets — even though Miami has the highest rates of office construction in the United States, according to the Miami Association of Realtors.
More high-net-worth individuals have migrated to Miami in recent years partly because there is no state income tax, at a time when California, New York and Washington State — the traditional hubs for the tech and finance industries — are proposing new levies on the ultrawealthy.
Ken Griffin moved his personal residence and the global headquarters of his hedge fund, Citadel, to Miami from Chicago in 2022. (He bought an entire city block in the Brickell financial district.) Mark Zuckerberg, Jeff Bezos and Mr. Brady have also all made Florida their home base. With these moves comes the need for family offices nearby. Mr. Brady’s family office, for example, is a roughly 15-minute drive from his home in Indian Creek Village, a neighborhood known as “Billionaire Bunker” in Miami-Dade County.
Family offices vary in size, but they can often be lean operations with just one or two family members working out of the space. On average, 15 employees work in a family office, according to Deloitte’s report, but larger firms can have a staff of more than 20 people.
Accounting firms, law offices and other white-collar firms that service family offices have taken notice and begun to open satellite branches around Miami to meet the demand.
“The talent pool in Miami has grown significantly,” said Ricardo Gonzalez, an international director of wealth management at UBS who is based in Miami. “The influx of experienced private bankers, investment professionals, tax experts, attorneys have made it very attractive for family offices.”

Developers have been changing their tactics to attract attention. Some new projects, including the Well, are focused on distinct identities such as wellness or art. And some buildings are created for multiple family offices.
“They all have a unique identity like you would find in New York City — SoHo is different than Midtown,” said Tere Blanca, the chief executive of Blanca, which represented the landlord and developer at the Well for several of the building’s signings. “Everyone decides what makes sense based on how aligned their brand is with that neighborhood,” she added.
Even with the momentum, those paying attention to the real estate market in Miami don’t think the city will become the next Wall Street or Silicon Valley.

“I don’t think Miami will ever compete with New York financial, I think they complement,” Mr. Tritt said. “Most of the families who live in California and New York that also live in Florida, I think they’re going to bifurcate.”
As for Miami’s current injection of fortune, Mr. Tritt said: “Wealth attracts wealth.”
Corrected on Aug. 2, 2026:
An earlier version of this article misstated where the billionaire Mohamed Mansour of Man Capital signed a family office lease. It was in the Well complex in Bay Harbor Islands, near Miami, not the Well complex in the Coconut Grove neighborhood.
We acknowledge mistakes in our reporting with corrections. If you spot an error, please let us know at corrections@nytimes.com.Learn more.
Emmett Lindner is a business reporter for The Times.


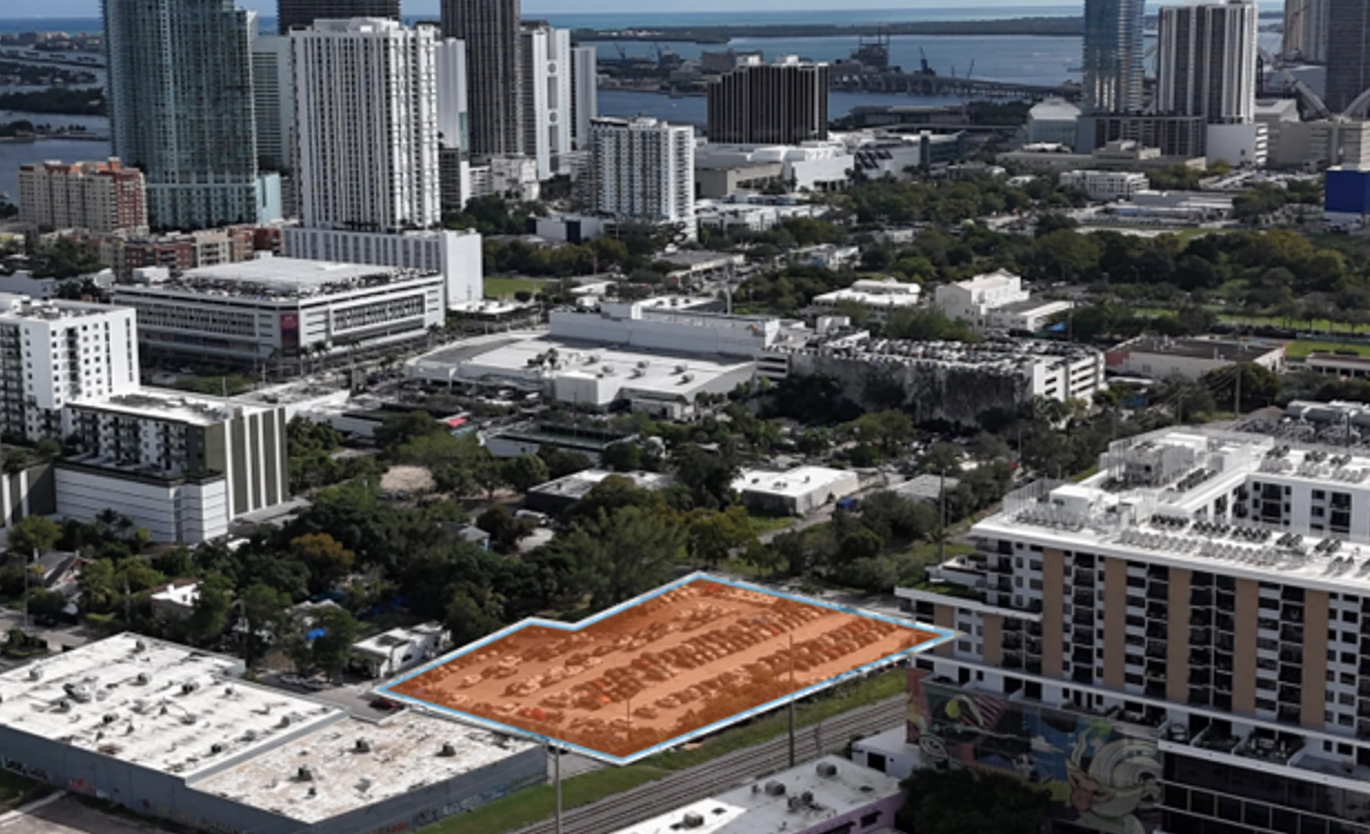
The sale equates to roughly $281 per square foot of land. Ursus Inc., which has since merged into 22 CO, sold the property to 110 NE 23rd Street Realty LLC. The purchase adds to a run of land trades along the Edgewater-Wynwood line, where large, assemblable sites have become increasingly scarce as both neighborhoods have filled in with new development. The Edgewater Development Site is among the largest single parcels to change hands in the area this year. “This stretch between Edgewater and Wynwood is one of the last places in the urban core where you can still assemble more than an acre under one zoning designation,” said Cary Cohen, Executive Vice President at Blanca Commercial Real Estate. “When a site like that comes together, it draws real competition, and that’s exactly what we saw here.” The site sits at 50, 60, 68 and 76 NE 23rd Street and 49 and 51 NE 22nd Street, within an Opportunity Zone and zoned T6-8-O, which allows up to 300 units per acre with a density boost the Miami City Commission approved for the neighborhood. The parcels also qualify for additional height and density under Florida’s Live Local Act. The site sits between Wynwood and Biscayne Bay, a few blocks from Margaret Pace Park. “Edgewater is running out of sites this size,” said Cohen. “The neighborhood has pulled in real capital since 2020, and the parcels large enough to support a ground-up project of any scale are getting harder to find every year. Buyers who can move quickly on land like this are proving that out in real time.” Edgewater has drawn roughly $500 million in property investment since 2020, according to Blanca CRE, as projects including Aria Reserve, Missoni Baia and Cove Miami have delivered or broken ground nearby. Developers can unlock additional density through a payment into the city’s Resilience Trust Fund. Key Facts Sale price: $16.5 million Buyer: Melo Group Property type: Development assemblage Location: North Miami Avenue and Northeast 13th Street, near Miami’s Edgewater neighborhood Total land area: Approximately 35,000 square feet Zoning: T6-24a-O mixed-use zoning Development potential: Up to 24 stories, with additional height potentially available through bonuses Future plans: No development proposal was announced at the time of the sale Share this entry You might also like CBRE Arranges New HQ Lease For Crystal Cruises Risk Management Company Inks Miami’s Largest Office Lease Transaction YTD Blanca Commercial Finalizes 31,500 SF Office Lease With Auto Insurance Carrier Blanca CRE Inks Nearly 50K SF Of New Leases, Renewals At O Towers Related And Shoma To Develop Mixed-Use Project New 11-Acre Mixed-Use Development In Downtown Miami Signs Two Major Office Tenants


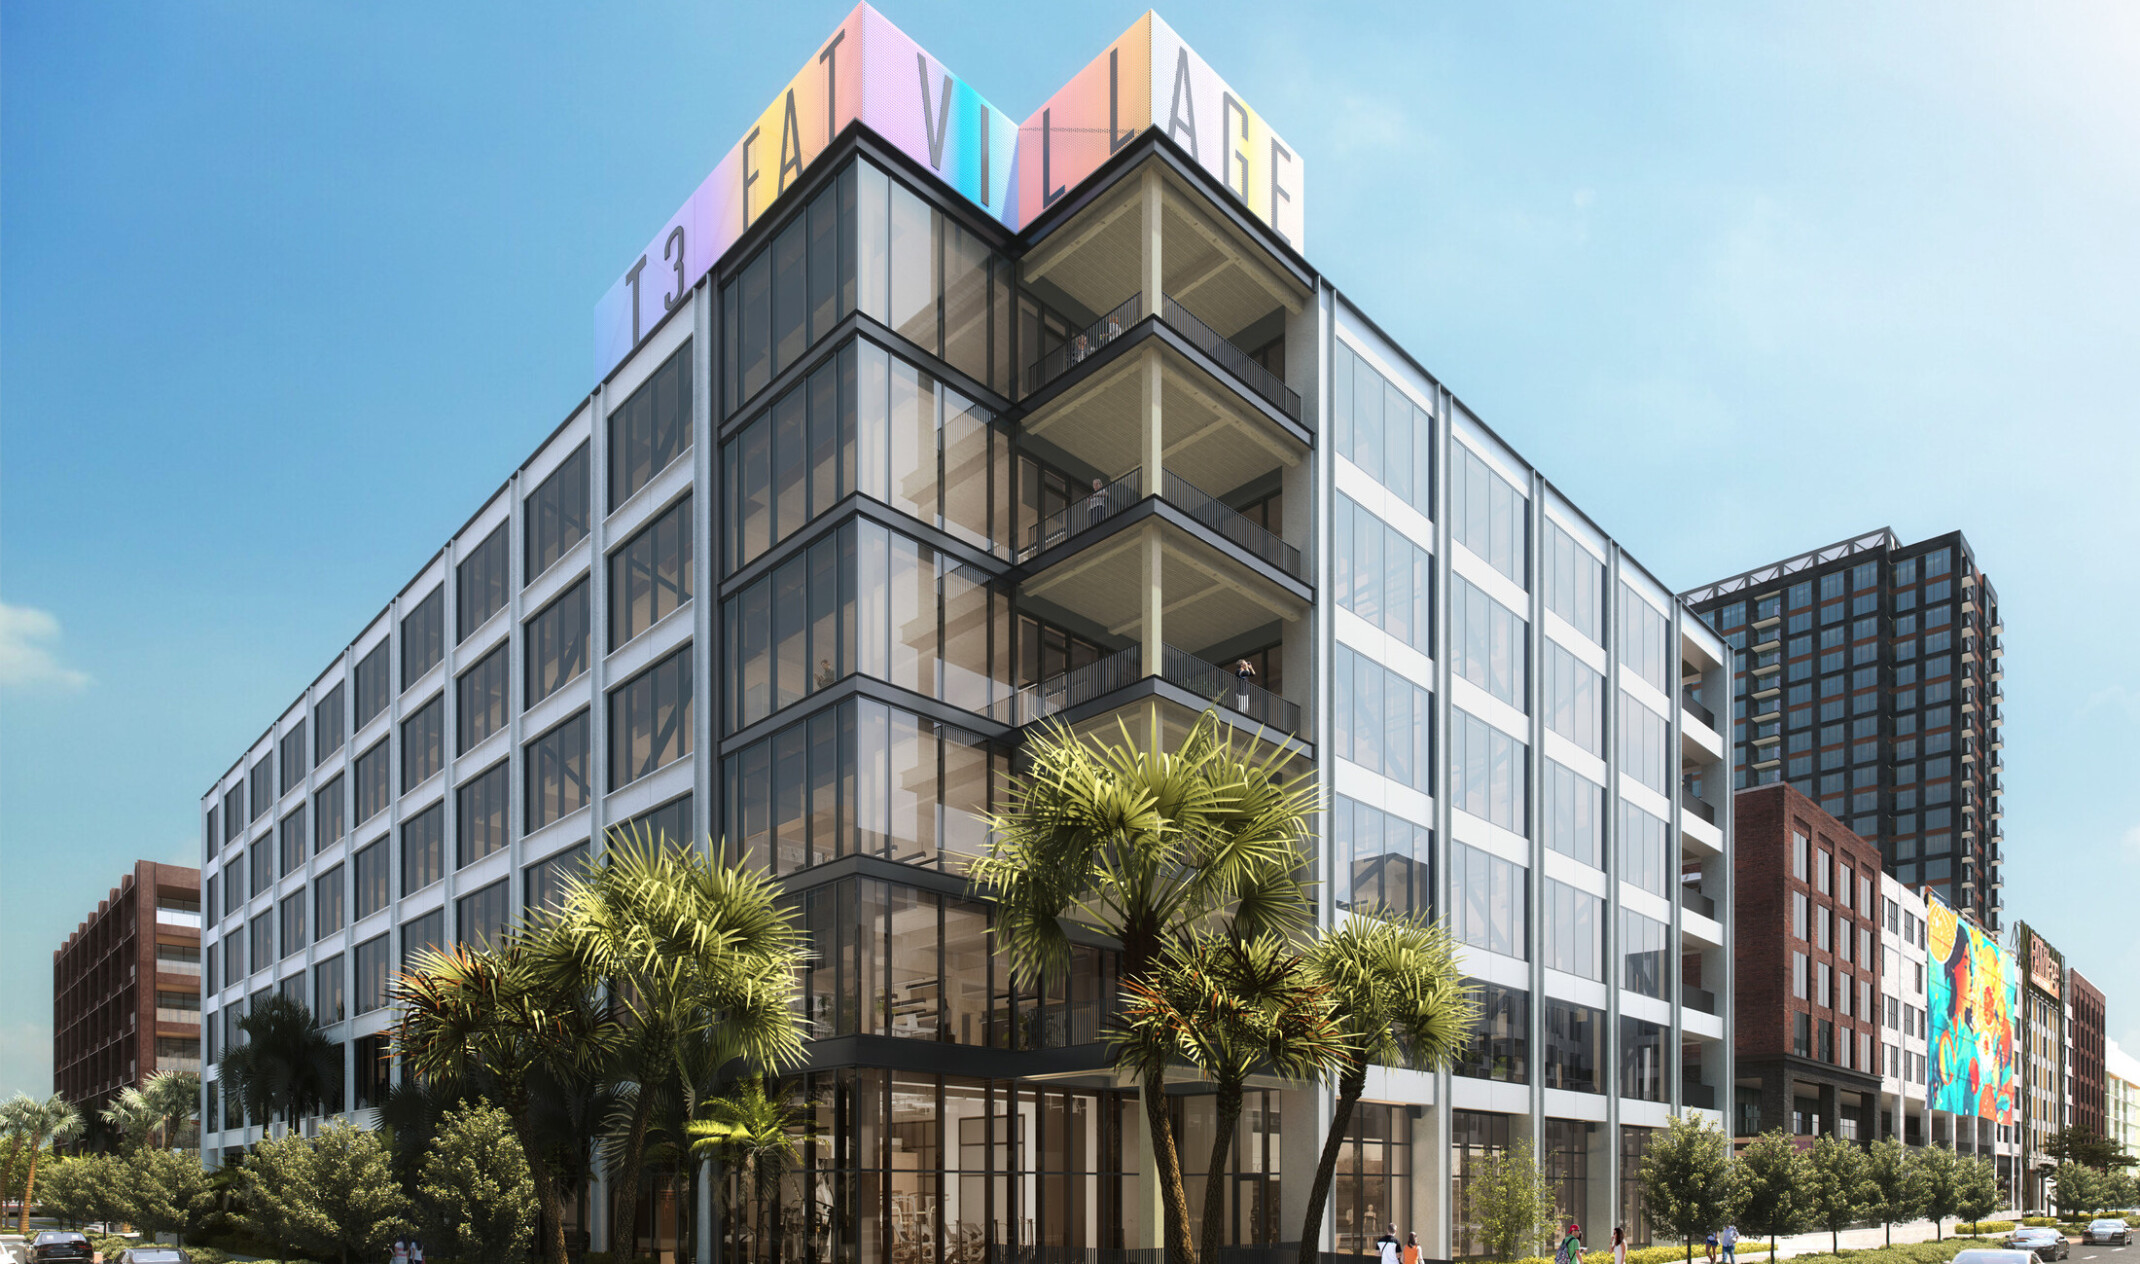
GXO Logistics and CBI Workplace Solutions have signed on as the first tenants in the new office building at FAT Village in Fort Lauderdale.

GXO expanded with new regional office, CBI relocated from Las Olas Boulevard
Get the latest property updates, market reports, and expert insights — delivered straight to your inbox.


